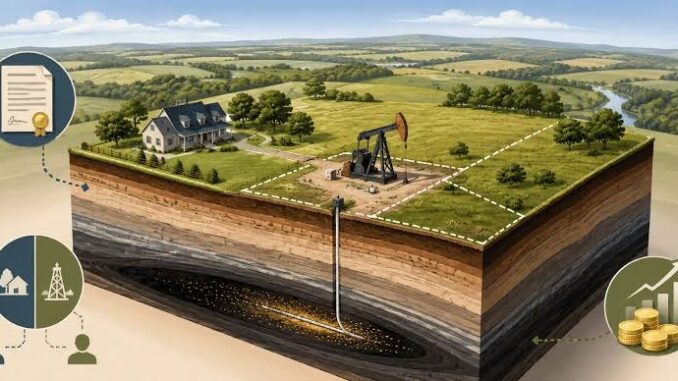
The COVID-19 pandemic delivered one of the sharpest shocks the oil and gas industry has ever seen. Prices collapsed in 2020, drilling activity cratered, and many mineral owners watched royalty checks shrink or disappear. Six years later, the picture looks different—more stable in traditional oil and gas, and dramatically more strategic when it comes to rare earths and other critical minerals. For mineral rights owners, the post-COVID era has brought both new opportunities and new complexities.
The Oil and Gas Side: From Crash to Steady Ground
The 2020 price crash forced operators to cut capital sharply. Leasing slowed, and some owners faced non-payment or delayed checks. Recovery followed as demand returned and U.S. production reasserted itself, particularly in the Permian and other shale basins. By the mid-2020s, oil prices settled into a more workable range for most producers (roughly the mid-$70s per barrel in early 2026 data), supporting continued drilling without the extremes of the 2022 spike.
Federal policy added layers of change. The Inflation Reduction Act of 2022 raised the minimum royalty rate on new onshore federal oil and gas leases from the long-standing 12.5% to 16.67%, increased minimum bids, and adjusted rental rates.
Those higher terms applied to leases issued in the window that followed. Later legislation in 2025 (commonly referenced as the One Big Beautiful Bill Act) rolled several of those changes back for new leases, restoring a 12.5% minimum royalty in many cases while leaving existing higher-rate leases in place. For private mineral owners, the practical effect is that federal terms influence competition and operator behavior even on fee lands, but negotiated private royalties continue to vary by basin, competition, and negotiation strength—typically still ranging from 12.5% to 25% in active plays.
Market activity for mineral rights themselves remained active into 2026. Buyers continued seeking producing and non-producing interests, though valuation multiples compressed somewhat from peak levels as interest rates and oil prices moderated. Owners who inherited interests or held long-term positions found more outreach from acquisition companies, making title hygiene and clear ownership records more important than ever.
Rare Earths and Critical Minerals: The Strategic Shift
COVID exposed supply-chain fragility across many sectors. Rare earth elements (REEs)—essential for permanent magnets in electric motors, wind turbines, defense systems, and electronics—highlighted a particular vulnerability. China has long dominated mining, processing, and magnet manufacturing. Export restrictions and geopolitical tensions in the years after 2020 accelerated U.S. efforts to rebuild domestic and allied capacity.
Policy responses intensified through the mid-2020s. The federal government moved beyond pure regulation into direct industrial policy: equity stakes in producers, price floors for key oxides such as neodymium-praseodymium, large financing packages, and the creation of a strategic critical minerals reserve (Project Vault and related initiatives). Companies developing domestic deposits—such as those tied to Round Top in Texas or expansions at Mountain Pass—received significant public support aimed at creating mine-to-magnet supply chains. Defense procurement rules further tightened requirements to reduce Chinese content in magnets by the late 2020s.
For private mineral owners, this creates a parallel opportunity. Rare earths and many other critical minerals fall under the General Mining Law of 1872 on most federal public domain lands (locatable minerals via claims) or under private ownership rules on fee land. Deeds that grant broad “mineral” rights can include REEs, though language limited strictly to oil and gas may not. Standard oil and gas lease forms are often a poor fit; hard-rock style agreements with different royalty structures (sometimes based on contained metal value or tonnage) are more appropriate. Environmental and processing issues differ significantly from conventional oil and gas operations.
Practical Impacts for Mineral Owners
Several post-COVID realities stand out for owners:
- Title and dormancy awareness remains critical. Severed mineral interests in states with dormant mineral statutes can still be at risk after long periods of non-use. Recording claims of interest, leasing, or other savings events continues to protect ownership. COVID-era inactivity in some areas may have pushed more interests closer to statutory deadlines in states that have them.
- Federal vs. private dynamics. Higher (and later partially rolled-back) federal royalties affected the competitive landscape but did not dictate private lease terms. Surface use agreements and accommodation doctrines continue to govern conflicts between mineral and surface estates.
- Dual-commodity potential. Properties with both hydrocarbon and critical mineral potential are attracting different kinds of interest. Owners should review their deeds carefully and consider whether separate leasing strategies make sense.
- Market transparency and buyer activity. More professional capital entered the mineral acquisition space. Clear division orders, accurate ownership decimals, and up-to-date contact information help owners capture full value whether selling or leasing.
- Broader energy transition pressures. Carbon storage projects and renewable development have raised new questions about pore space and surface use, sometimes intersecting with traditional mineral dominance doctrines. In several states the mineral estate remains dominant, requiring careful negotiation for CCS or other subsurface uses.
Looking Ahead
The post-COVID period has not rewritten the fundamental U.S. system of private mineral ownership—one of the country’s distinctive advantages. It has, however, layered new policy tools, strategic priorities, and market participants onto that foundation. Oil and gas mineral owners who weathered the 2020 crash generally returned to more predictable cash flow environments by the mid-2020s. At the same time, the rare earth and critical minerals push has opened a second front of potential value for those whose rights extend beyond hydrocarbons.
For owners, the practical steps remain familiar but more urgent: know exactly what you own (and in which state), keep records current, understand local dormant mineral rules, and approach any lease or sale with professional title and legal review. The landscape after COVID rewards attentiveness more than it did in quieter decades.
This overview is for informational purposes and does not constitute legal, tax, or investment advice. Mineral rights are governed primarily by state law and specific deed language; consult qualified professionals for individual situations.
Jason Spiess is the founder of The Crude Life and has been an working-owner in media companies for over 40 years.

The Crude Life Content Network
Primary Website
Follow on YouTube
Follow on Facebook
- The Crude Life Facebook Page
- Eagle Ford Texas Facebook Page
- Bakken.com Facebook Page
- Haynesville Facebook Page
- Marcellus Facebook Page
- Niobrarachalk Facebook Page
- PermianShale Facebook Page
Follow on LinkedIn
- The Crude Life LinkedIn
- The Founder of The Crude Life – Jason Spiess LinkedIn
The Crude Life has been a trusted brand pioneering energy content for 15 years — from the very first podcast in 2011 to today’s full-spectrum content company producing podcasts, video interviews, print features, radio news, social media campaigns, Substack editorials, live events and more.
Trusted Interviews. Industry Experts.